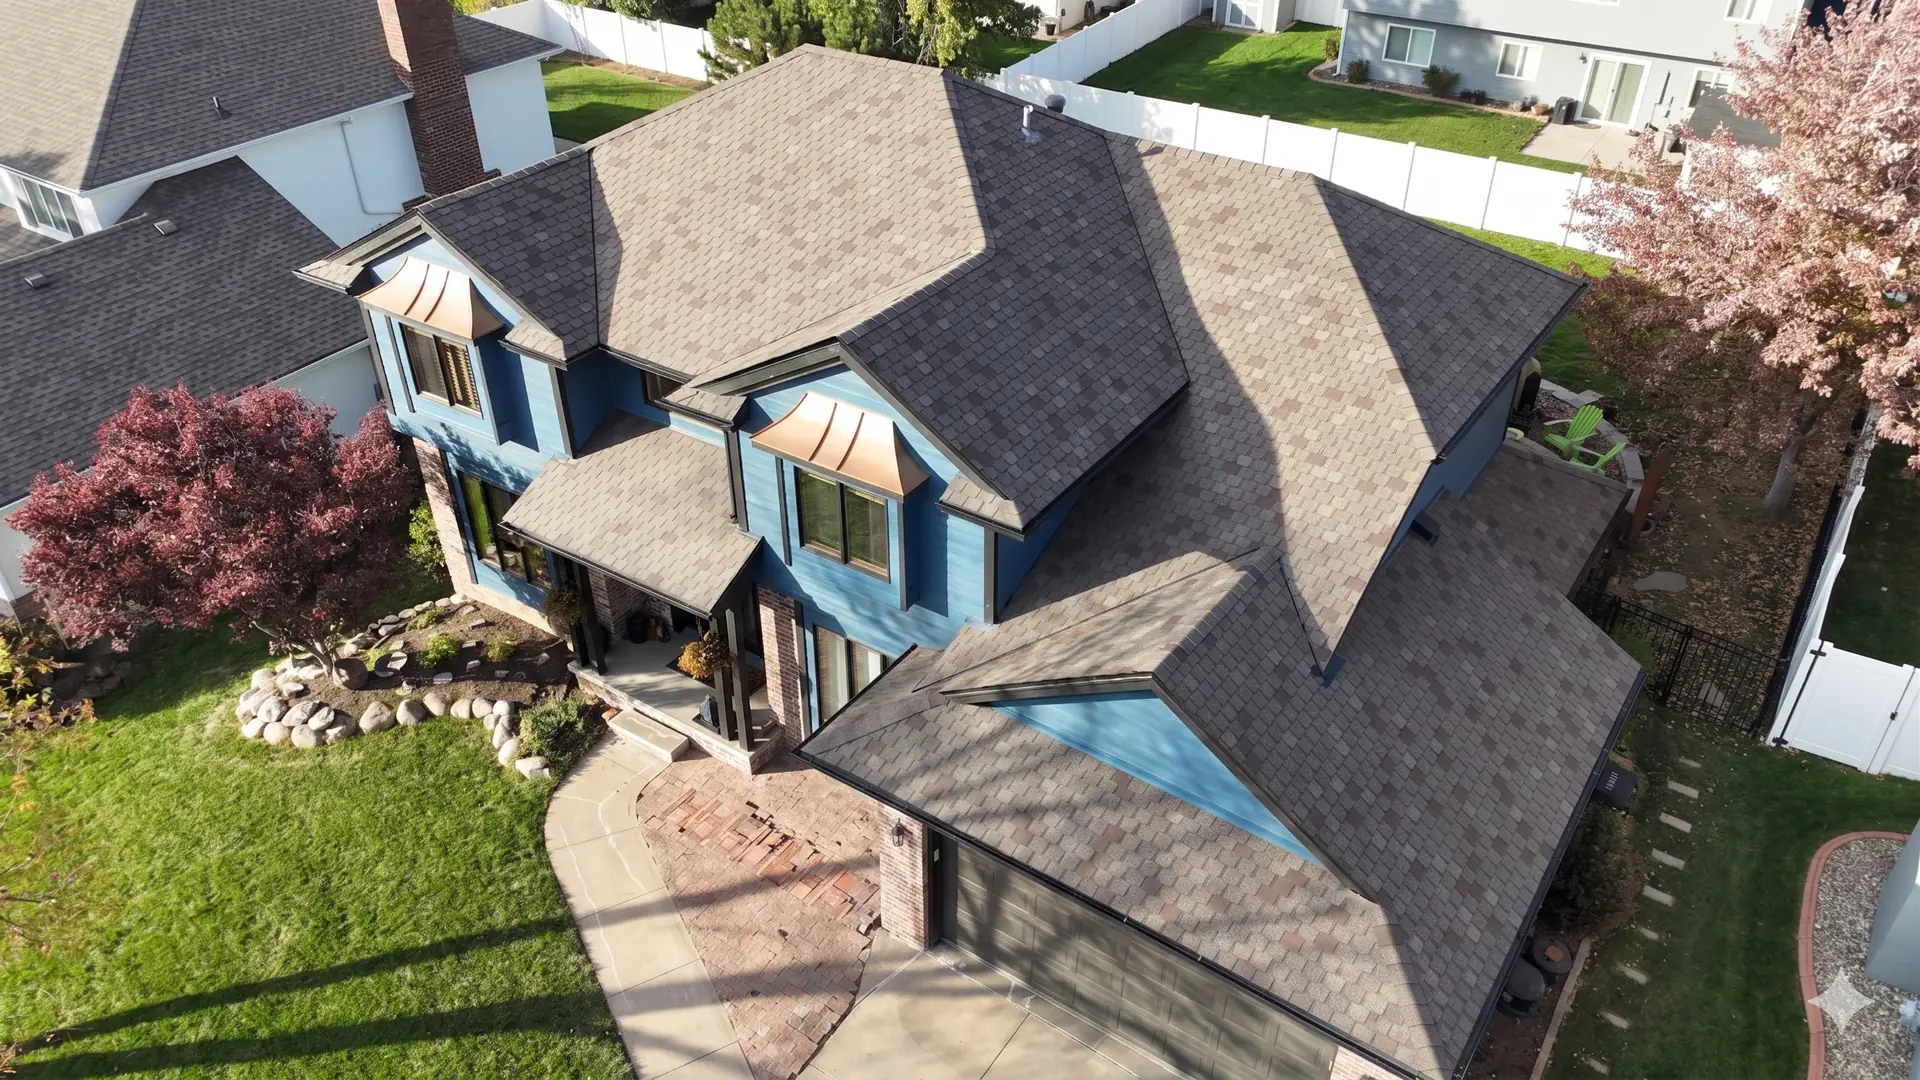
Learn how to file a roof insurance claim in Lee's Summit, including deductibles, documentation, and timing, from Capstone Contracting.
Filing a roof insurance claim in Lee's Summit starts with a documented inspection, not a phone call to your insurer. After this year's spring and late-summer hail, we've met homeowners who waited months, only to find their window for filing had gotten tighter. Here's how the process actually works, and what to check before you call.
What's the Quick Answer for Filing a Roof Insurance Claim in Lee's Summit?
Get a professional, photo-documented inspection first, then check your policy's declarations page for your wind or hail deductible before you call your insurer. Most Missouri policies use a separate, often higher deductible for storm damage, and some carriers set their own notice windows for filing after a storm, so don't assume you have unlimited time. Once you file, an adjuster will schedule a visit, and having your own contractor's documentation ready makes that meeting faster and more accurate. Nothing about filing a claim commits you to using a specific contractor, and nothing guarantees a specific payout.
What Homeowners Usually Notice First
Most Lee's Summit homeowners don't start the claims process because they saw hail hit their roof. They start it because someone else brought it up. A neighbor mentions their own roof insurance claim after a storm. A contractor knocks on the door pointing out a bent gutter. Or a homeowner simply notices granules building up in a downspout and starts wondering if it's worth a look.
By the time most people think about filing, weeks or months have often passed since the actual storm. That gap matters more than people realize. The damage doesn't get better with time, and the paperwork trail gets harder to piece together the longer you wait.
We also hear a lot of confusion about what actually triggers a valid roof insurance claim in Lee's Summit. Age-related wear, like curling shingles from years of sun exposure, typically isn't covered. Sudden storm damage, like hail bruising or wind-lifted shingles from a specific, datable event, usually is. The difference matters for how the claim gets evaluated.
It also matters because adjusters look for a datable cause, not just visible damage. A roof that's simply old and worn can show granule loss and curling shingles that look similar to storm damage at first glance. Tying the damage to a specific storm date, with local hail or wind reports to back it up, is often what separates an approved claim from a denied one.
What a Roofing Contractor Looks For
On many pre-claim inspections we run in Lee's Summit, the first thing we do is separate storm damage from ordinary wear, because that distinction drives the entire claim. We look for the small, circular bruises and hail leaves on shingles, where the granules have been knocked loose and the mat underneath is exposed. We check soft metals like vents, flashing, and gutter edges too, since they dent more easily than asphalt and often confirm that a storm actually hit hard enough to matter.
What homeowners often miss is that the inspection report itself becomes part of the claim file. A written, photo-documented scope, with each area of damage labeled and dated, gives the adjuster something concrete to work from instead of a verbal description. We also walk the roof with a chalk test in mind for hail bruising, marking impact points so nothing gets missed once we're back on the ground.
One Lee's Summit homeowner called us after a summer storm, unsure whether the damage was worth reporting. Their roof was ten years old, and they assumed insurance wouldn't cover anything that wasn't brand new. When we inspected it, we found clear hail bruising across two slopes, consistent with a storm reported in their zip code weeks earlier. The age of the roof wasn't the issue. The cause of the damage was, and that's what carriers evaluate.
What Documentation Actually Helps Your Claim
A written inspection report is only part of what strengthens a roof insurance claim in Lee's Summit. Clear, dated photos of every damaged area, taken from multiple angles, give an adjuster something specific to reference instead of a general description. Photos of soft metal damage, like dented vents or gutters, matter too, since they help establish that a storm hit hard enough to affect the whole roof, not just one isolated spot.
Keeping a simple timeline also helps. Note the date of the storm, when you first noticed damage, and when you scheduled your inspection. This isn't about building a legal case. It's about giving your insurer a clear, consistent story that matches what they can independently verify through local weather records.
Common Mistakes Homeowners Make
The most common mistake is waiting too long after a storm to get an inspection. Some Missouri carriers require notice within a set window, and that window varies by policy, so checking your own declarations page early matters more than guessing based on what a neighbor's policy said.
The second mistake is assuming a repair estimate and an insurance claim are the same conversation. They aren't. A free inspection and a written scope of damage give you information. Whether you file a roof insurance claim in Lee's Summit with that information, or simply pay for a smaller repair out of pocket, is your decision, not a decision a contractor makes for you.
The third mistake is not understanding the difference between actual cash value and replacement cost value coverage before the adjuster shows up. These terms affect how much you're paid and when. Your own policy defines which one applies to you, so read that section, or ask your agent directly, rather than assuming either applies.
The fourth mistake is attempting a full DIY repair before documenting the damage. A quick tarp to stop an active leak is reasonable and often necessary. Replacing shingles yourself before anyone has photographed the original damage can make it harder to prove what the storm actually did, which can complicate the claim later.
How to Decide Whether to File
Not every storm-related roof issue is worth a formal claim. If the repair cost is close to or lower than your deductible, filing may not make financial sense, since you'd likely pay close to the full amount either way. If the damage is widespread, spans multiple roof slopes, or affects an older roof already nearing the end of its life, filing usually makes more sense.
A documented inspection helps you see which situation you're actually in, instead of guessing. That's the real value of getting a professional look before you decide anything.
Local Weather Context for Lee's Summit Roofs
Lee's Summit sits in one of the more storm-active corridors in the Midwest. NOAA's Storm Prediction Center shows the Kansas City metro's hail activity peaks in spring, typically March through May, but late-summer events still happen regularly. The metro saw golf-ball-sized hail as recently as August 19, 2026, a reminder that storm season doesn't fully wind down before fall arrives.
That overlap creates a real problem for homeowners who put off inspections. A roof damaged in August has already sat through weeks of temperature swings by the time October rolls around. Once nights start dropping toward freezing, any crack or bruise from that storm gets worse every time moisture inside it freezes and expands, which can turn a claim-worthy repair into a full replacement by the time anyone gets around to filing.
What to Do Before You Call Your Insurer
Before you pick up the phone, get a free, photo-documented roof inspection so you know what you're actually dealing with. Capstone's inspections are owner-managed, meaning Rebekah or a member of her team walks the roof directly and gives you an honest read, not a sales pitch designed to push a claim you may not need. That direct involvement matters most in exactly this kind of decision, where a rushed or generic inspection can lead a homeowner to either overlook real damage or file a claim that never should have been filed in the first place.
If it turns out filing makes sense, our insurance claims assistance team can meet your adjuster on-site and walk through the documentation together. If you'd rather talk it through in person first, visit us in Grain Valley, MO, or call to schedule your free inspection before winter weather complicates the process further.
Frequently Asked Questions
How long do I have to file a roof insurance claim in Lee's Summit after a storm?
It depends entirely on your policy. Some Missouri carriers require notice within a specific window after the storm date, while others are more flexible. Check your declarations page or call your agent directly rather than relying on a general rule, since this detail varies significantly between carriers.
Will filing a roof insurance claim in Lee's Summit raise my premium?
Hail and wind claims are typically treated as weather events rather than at-fault claims, and a single legitimate claim usually doesn't raise premiums the way an at-fault claim would. However, multiple claims within a few years can affect insurability with some carriers, so this is worth discussing with your agent for your specific situation.
What's the difference between actual cash value and replacement cost value for my claim?
Replacement cost value generally covers the cost of new materials, while actual cash value factors in depreciation based on your roof's age. This distinction significantly affects your payout, and it's defined in your own policy, not something a contractor can determine for you. Always confirm which one applies before you file.
Do I need a contractor's inspection before I call my insurance company?
It's not required, but it's strongly recommended. Hail damage often looks minor from the ground and can be missed entirely by an untrained eye. A documented inspection gives you and the adjuster a shared, accurate starting point, which tends to make the entire process faster.
Can Capstone guarantee my claim will be approved?
No, and any contractor who tells you otherwise should raise a red flag. We can document damage thoroughly and meet your adjuster on-site, but the approval decision belongs entirely to your insurance company based on your policy's terms. What we can promise is an honest inspection and clear documentation, which gives your claim the strongest possible starting point.
Rebekah Saettone, Founder and CEO. Woman-owned roofing in Greater Kansas City since day one.
